
15 Best Ways to Improve Your Working Capital
Summary
Key Takeaways
- Know your numbers: Working capital = current assets − current liabilities. Working capital ratio = current assets ÷ current liabilities.
- Collect faster: Reward on-time payers, set late-payment penalties, segment customers by credit risk, and resolve disputes quickly.
- Pay smarter: Negotiate longer payment terms, and take early-payment discounts when they make sense.
- Cut costs: Review monthly expenses, avoid overstocking, and reduce interest and penalty costs on existing debt.
- Use data and automation: Digitize inventory, billing, and payments to spot problems early and reduce errors.
- Keep a buffer: A business credit line can cover short-term gaps without tying up your cash.
Last updated: October 24, 2020
Now is the best time to closely monitor your business’ financial structure. Among the important things you should be familiar with in managing your own business is where to get financing and how you can manage your working capital. By sorting out these basic requirements, you will be able to easily gauge the growth of your business.
Working capital, also called Net Working Capital (NWC), is your business’s current assets (such as cash, receivables, and inventory) minus its current liabilities (such as payables and short-term debt). It measures your business’s capacity to meet its short-term financial obligations. Therefore, running short on working capital will not only add to your stress but will also cause inefficiencies in your business operations.
Your business’s wages, accounts payable, facility expenses, and payment to suppliers can be met more efficiently when your business’ working capital is properly monitored and handled. This is the reason why businesses who excel in their field industries always look for ways to manage and improve their working capital position. By having adequate working capital, you send out a message that your business has sound management, which, in turn, can earn the trust of stakeholders and satisfy the expectations of investors and shareholders.
With this, here are the 15 things you have to do to improve your working capital:
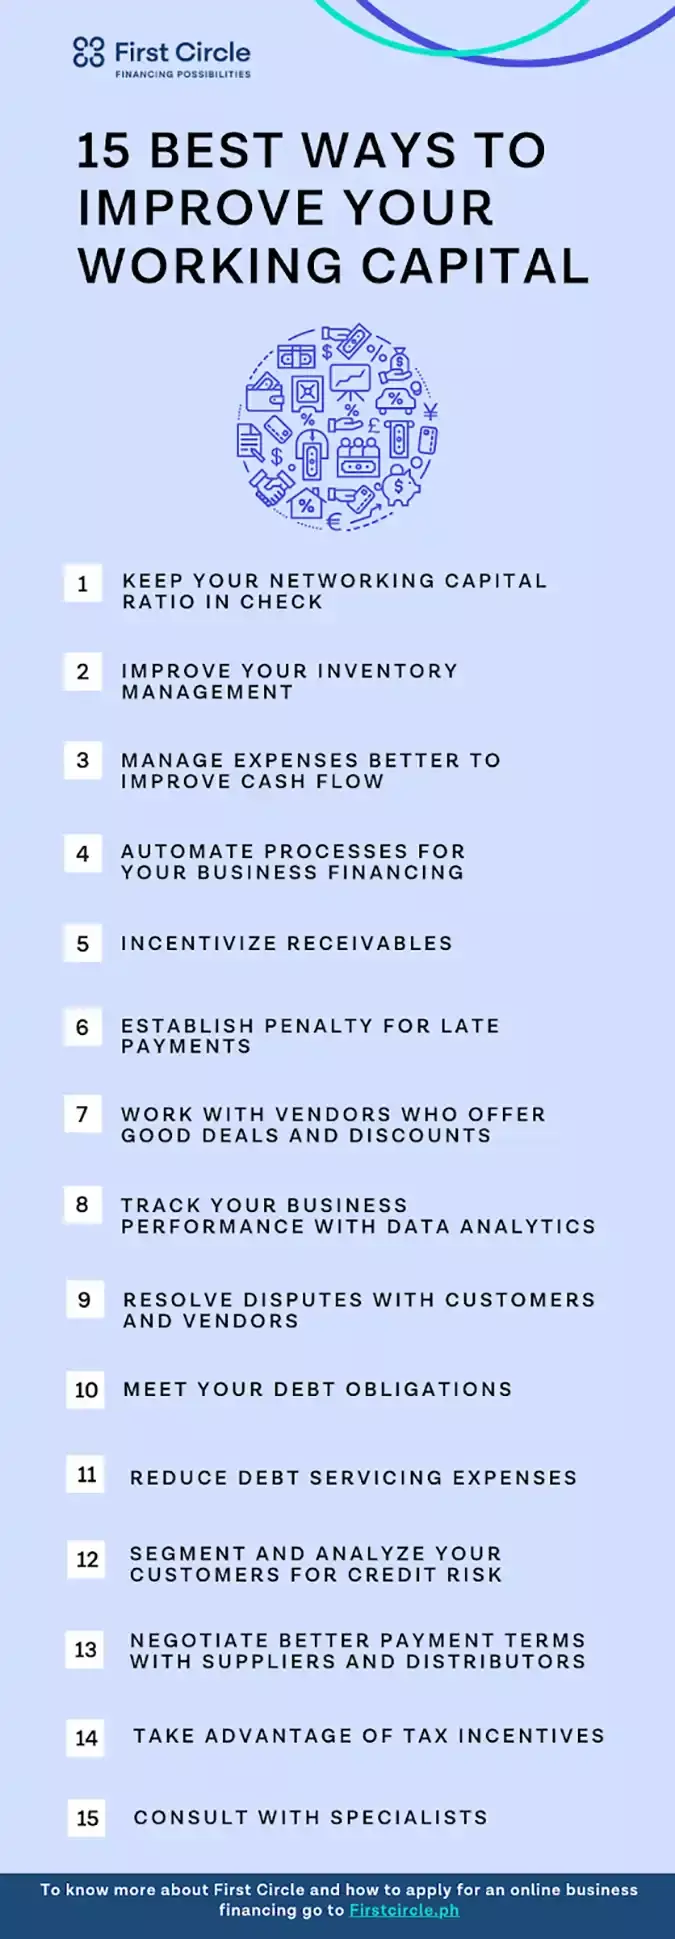
1) Keep your net working capital ratio in check
Set your goal to get a good NWC ratio. You can calculate your working capital ratio using the same numbers you used in your NWC with this formula: working capital ratio = current assets / current liabilities.
A working capital ratio of 1.0 or less means your current liabilities are equal to or greater than your current assets, which leaves you with little or no room for adjustment. This becomes a problem when a client fails to pay you on time and when some other unexpected expense comes up.
On the other hand, getting a 2.0 or higher quotient could mean that you’re not making the most of your resources on hand. You might need to re-evaluate your budget and see if you can invest in new equipment or spend on more aggressive marketing, which will actually help your business grow or gain an edge over your competition.
Some businesses overlook their working capital ratio because they just see it as additional work, but for any serious business that wants to establish trust with its shareholders and secure additional funding for future growth, having a stellar working capital ratio is important.
The ratio determines the effectiveness of your business’s growth plan and whether your business has enough short-term assets to pay off its short-term debt. It also provides a measurable basis to secure business financing by reflecting the efficient handling of your business’s resources.
2) Improve your inventory management
Inventory is one of your business’s current assets, which makes it part of your working capital. How you manage your inventory can also impact your working capital. Your inventory consists of items that are held for sale, items that are being prepared for sale, and items used in the production process.
The inventory is one of the things being checked by investors and shareholders to determine the operational efficiency and viability of your business. Too much inventory ties up cash that could be used elsewhere, and adds costs like warehousing, spoilage, and waste. Too little inventory, on the other hand, can lead to stockouts and lost sales.
Reducing excess inventory can free up cash, but cutting too much can hurt your ability to fulfill orders. Efficient inventory management, which means keeping just enough stock to meet demand, is the most effective way to optimize your working capital.
It is advisable to invest in digitizing your inventory management to help you optimize your inventory by tracking orders, deliveries, and sales. This saves you from overstocking and inventory shortage. It may be expensive, but it can increase business efficiency in the long run. Digitized inventory management can minimize losses and business interruptions through an effective warehouse organization.
3) Manage expenses better to improve cash flow
Cash flow is the ultimate value driver in any business. With this, your working capital is highly affected when assets are tied up in things like inventory or unpaid invoices. In business financing, having negative cash often scares investors and shareholders away and this can result in undervaluation of a business if not remedied. In the worst cases, businesses become unable to pay their bills and may be forced out of business.
Pay attention to your cash flow and compare it with your expenses such as bills and equipment purchases. Often, heavy equipment purchases and lags between providing services and receiving payment cause a major strain in business cash flow.
Find out if there are areas where costs can be further reduced. Start by going through all of your monthly subscriptions. That way, you can identify which expenses are wasteful and which expenses you have to eliminate in order to increase the liquidity of your working capital. You have to take note, though, that cost-cutting without considering the real needs and demands of your employees, customers, and partner vendors may produce short-term benefits, but with poor long-term results.
To learn more, read our guide to working capital.
4) Automate processes for your business financing
Manually handling your business financing processes is labor-intensive, inefficient, and error-prone. It requires you to hire people who specialize in a certain aspect of your business. Hiring specialists prove helpful for your business to thrive as specialists have keener eyes for small details you might overlook. However, it becomes tricky when your key employees suddenly quit — you need to hire and train new people to transfer their knowledge about manual handling.
Automate your accounts to eliminate expensive labor costs and errors. While manual management can add cause to delays in getting paid, automation saves money in the long run and reflects up-to-date business financing processes in your business.
This may require you to outsource a strong collection team, which could mean giving up a degree of control and visibility. You will be able to track cash inflows and outflows with ease and your outsourced team can provide your customers with a digital platform for invoices and payments. However, you’ll become more dependent on them as you no longer control how they handle your accounts processes.
Learn more about using free online tools to automate your processes by clicking here.
5) Incentivize receivables
As a business owner, you have to also establish working relationships with your customers, suppliers, and vendors, among others to ensure that your business doesn’t suffer from unreliable people who do not promptly fulfill their obligations.
Having your business accounts automated can help you by determining the customers who pay on time. Give incentives to these kinds of customers to encourage them more into meeting their payment obligations. This will not only allow you to establish a good rapport with your customers but will also help you hold a good capital position.
Proper monitoring and investigation are key in keeping your accounts up-to-date. Balance the assessment of your customers’ creditworthiness to protect your business from being vulnerable to negative cash flow and bad debts.
6) Establish penalty for late payments
As much as you incentivize timely fulfillment of payment obligations, you also have to establish a penalty for late-paying customers. This move sends out a message to your customers that they should meet their payment obligations punctually. This also allows you to get invoices paid faster.
While penalties can add to your collectibles, it also serves as a mitigating factor for customers who pay late. Prior to implementation, ensure that your customers are completely on board with your policies such as imposing late fees. If not, imposing penalties for late payments may also jeopardize your working relationship with your customers, which may result in your business not achieving its desired outcomes.
7) Work with vendors who offer good deals and discounts
Establishing a good working relationship with your vendors will not only help you get special deals discounts but will also help you earn your vendor’s trust. When the time comes that your business faces a cash flow crunch, your relationship will go a long way in receiving some leniency.
Take advantage of early payments as an opportunity to negotiate about getting discounts. This way, not only will you have a good standing for your payables, but will also save you some expenses that could help you pay debts and grow your working capital.
Just make sure to keep up with your suppliers’ terms and conditions to avoid hurting your finances and credit standing in the long run. Failing to do so would make it difficult or even impossible to get business financing for growth or, worse, during an emergency.
8) Track your business performance with data analytics
Most businesses are now transitioning to data-driven business management and decision-making because numbers provide amore reliable basis for business decisions. Looking for business financing opportunities would be much easier for you if you have enough data to back up your claims and promises to potential investors or loan providers.
Collecting data is just one of the processes of data analytics. Aside from having data, you have to make sense of the data you have to make it work for your business.
One of the benefits of data analytics is that it eases up the management of your working capital, creation of management reports, compliance monitoring across business departments, and review of your operations. It allows you to have a more comprehensive review of how your business operations whether it is consistent with your business financing goals. Metrics should be customized to measure your milestones so you can gauge whether you are off or on target when it comes to your business goals.
In setting up data analytics for your business, it is important that you determine the right metrics that will allow you to properly gauge whether an aspect of your business needs recalibration. Poorly defined metrics and lag in real-time data can derail rather than help you achieve your goal. Make sure that your audit team collects up-to-date data to foresee the challenges and opportunities ahead of you.
9) Resolve disputes with customers and vendors
Business financing requires more than knowledge about money. Part of growing your working capital is the proper handling of relationships essential to your business. As you grow your business and transact with more people, the chance of a discrepancy occurring is always high so it is inevitable to have disputes.
Maintain your good rapport with customers, clients, and partners by resolving disputes quickly. There may be some cases that are likely brought to the court at some point, but as much as possible, it’s always better to avoid the undue delay of resolving disputes to prevent unnecessary legal expenses.
When disputes aren’t quickly addressed, receivables are subject to the freeze, which is often a concern for many organizations. To avoid this, go through the policies and agreements of your customers and suppliers. Look for what’s missing, what isn’t clear, and where potential areas for conflict exist.
This requires more customer service legwork and training in addressing conflicts (i.e. getting involved with conflict resolution). In turn, the experience can give you the upper hand to healthily resolve conflicts in the future and it will save you money and your employees’ time, all of which deplete working capital.
10) Meet your debt obligations
The way you manage your debts can also affect your working capital position. Manual processing is often the reason why late or missing debt payments happen, hence the penalties. Some penalties seem harmless but when late payments become a regular habit due to mismanagement of debts, it will likely deplete your working capital in the long run.
Ensure that you pay your debts on time to avoid delays and penalties. Electronic payment systems can help manage your dues so that your payments are timely. That way, you can dodge the late fees and maintain your good credit score at the same time, which can put you in advantage when applying for loans in the future.
This works best when you limit your business to small amounts of debts only. Having too much debt makes it much harder to meet due dates on time. Considerable factors include delayed receivables and short payables cycle.
11) Reduce debt servicing expenses
For small businesses and startups, debt can be unavoidable as it is usually and initially an indispensable part of growing your working capital. However, make it part of your business goal to establish a better financial structure so that it is much easier for you to secure business financing when needed.
Analyze your capability to secure business financing and examine whether you’re paying too much on interest with your existing ones. The way you manage your financial obligations has an immediate impact on your working capital as this can also turn your cash flow to zero if you overlook details such as exorbitant penalties and interests when you settle your loans.
Know the business financing options available to you and learn to always look at the fine prints on each business financing opportunity being offered to you. When secure business financing, negotiate better rates and lower interest rates. Try to get a fixed-rate line of credit without any origination fees.
Locally, First Circle offers a Business Credit Line that can help with working capital needs. It requires no collateral, has no application fees, and you only pay when you use it.
Meanwhile, a sound business financing plan requires you to take loans only when needed. It is dangerous to develop the habit of taking out additional loans just because you want to capitalize on low-interest rates. Taking care of a pile of loans can increase the likelihood of your business incurring penalties due to mismanagement of debts because of late or missed payments.
If you want a more thorough comparison of business loans, read our guide to the 12 Sources of Business Loans in the Philippines.
12) Segment and analyze your customers for credit risk
Automating your business’ billing process and providing an online payment portal can give you the edge in business financing by making data collection from your transactions programmed. Data can help you identify your customers and segment them by their likelihood to repay you. This allows you to optimize your collections and improve cash flow in the long run. You can also do this to your distributors so you can analyze whether they are likely to sell to customers that don’t pay.
Complement your analysis by adjusting your customers’ and vendors’ credit profiles and terms or adding penalties and incentives. As previously discussed, incentivizing receivables and establishing penalties could make a room for on-time payments and more cash inflows.
This allows you to create projections of how likely your customers will miss payments. This way, you would know who among them you are more comfortable continuing to do business with in order to avoid disputes in the long run. However, do all these with proper metrics and sound collection policies to prevent personal bias from influencing your decisions. Without a solid and consistent basis, this could result in alienating your customers who paid late but are generally good to have business with.
13) Negotiate better payment terms with suppliers and distributors
Business financing is also about negotiation, which includes negotiating better payment terms and pricing. Improve your payment processes by occasionally reviewing all supplier contracts so you can ask for better pricing whenever possible.
While some suppliers are easy to deal with, others won’t budge to negotiate more favorable terms. Analyze the situation to know when you might need to replace your supplier. Loyalty is a good characteristic but always keep in mind that your decision-making should be biased-proof to get the best working capital position for your business to survive.
You should also address the gap between your accounts receivable and payable. Negotiate better due dates with suppliers by lengthening the payables cycle. To avoid draining your working capital, make sure to avoid paying before the due date until all the obligations of suppliers are fulfilled.
Establishing a balance between terms for receivables and payables will result in the most efficient cash flow. Just make sure that all obligations on your end are met on time. Failing to do so might lead to suppliers and distributors dropping you.
14) Take advantage of tax incentives
The regularity and punctuality in paying your business taxes reflect your business’s financial situation. Apart from being a law-abiding entrepreneur, fidelity in settling your tax obligations can also help you secure more tax incentives. Staying compliant also helps you avoid surcharges, interest, and penalties, and keeps your business eligible for tax incentives and programs that require good standing. Micro and small taxpayers, for example, now enjoy reduced penalties under the Ease of Paying Taxes Act.
Although some incentives make little to no difference, especially location-specific taxes such as wages, utilities, and transportation costs, allowing your business to take advantage of tax incentives from time to time will likely affect your working capital position.
On the other hand, being conscious of your business tax payments can also help you prevent overpaying your taxes. Either way, whatever you save from efficient tax payment can be channeled into the working capital funds.
15) Consult with specialists
You are an expert in your field and that’s why you have your own business. Among the pitfalls of being a business owner is the hubris that you know all that there is to know about your business.
The most effective leaders know when to ask for help. There are aspects of your business operations that are better off automated, but you should also get people who can work with you in growing your business. Getting specialists allows you to have more trained eyes to assess what your business needs to grow.
There is a growing trend among big businesses and startups to get outsourced specialists, instead of hiring in-house. This move mitigates the risk of losing in-house employees who could jeopardize business continuity because of being too dependent on the expertise of a single person or department while enjoying the benefits of having experienced and trained people with you as you run your business.Crucial aspects of business operations such as accounting, legal, IT, data analysts, and human resources can be outsourced to third-party firms with dedicated people who can expertly handle the job. By outsourcing such services, you enjoy benefits such as:
1) taking off from your shoulders the burden of determining whether a person is qualified for the job or not;
2) not needing to provide employee training or to wait for them to adjust to your work demands; and,
3) lean business organization.
These consultants can bring in their in-depth expertise required for your organization. They can offer neutrality which you need for unbiased and objective business decision-making.
In relation to ensuring that your working capital is well managed and your business is viable enough to secure business financing in the future, you can also outsource experts to work with you in evaluating what you need and where to improve in your business.
Financing partners can also help when clients’ orders are too large to fulfill or when customer payments take too long. First Circle’s Business Credit Line, for example, requires no collateral, so you can access funds for larger orders or cash flow gaps without putting your assets at risk.
Always remember that your vision as a business owner is the force that sets your business to motion, but it is the decisions that you make along the way that will keep it moving towards the direction you wish it to turn. Make informed and guided decisions to accomplish your goals.
Ultimately, data analytics and getting experts behind your business is what you need to improve your working capital. Making your business smart through data-driven decision making, relationship building, and operations management is what can set your business up to take on more aggressive growth opportunities.
Need business financing today? First Circle, an official DTI financing partner since 2018, offers a non-collateral Business Credit Line for SMEs. Apply online here.
Frequently Asked Questions
What is working capital?
Working capital, or net working capital, is your business’s current assets minus its current liabilities. It shows whether your business has enough short-term resources, such as cash, receivables, and inventory, to cover short-term obligations like supplier bills, wages, and loan payments.
How do you compute the working capital ratio?
Divide your current assets by your current liabilities. A ratio below 1.0 means your short-term debts exceed your short-term assets, which can make it hard to pay bills on time. A ratio above 2.0 may mean you’re holding too much idle cash or inventory that could be put to better use.
What causes working capital problems?
Common causes include customers paying late, too much cash tied up in slow-moving inventory, short payment terms with suppliers, high interest and penalty costs, and large unplanned expenses or equipment purchases.
How can I improve my working capital quickly?
Focus on collecting overdue receivables, cutting unnecessary expenses, negotiating longer payment terms with suppliers, and selling slow-moving inventory. A business credit line can also give you a quick buffer while these changes take effect.
Can a business credit line help with working capital?
Yes. A business credit line gives you access to funds you can draw on when cash runs short, such as while waiting for customer payments or fulfilling a large order. You only pay interest on the amount you use, so it works as a safety net for your working capital.
Loan product information, interest rates, and eligibility criteria for First Circle as of date of publication are subject to change at any time without notice. First Circle Growth Finance Corp. is a financing company with SEC Registration No. CS201605477 and CA No. 1108. It is regulated by the Securities and Exchange Commission with the email flcd_queries@sec.gov.ph. For any questions, you may reach out to support@firstcircle.com.

Jess Jacutan
Get started with First Circle today
Apply for an account online in 5 minutes
Simply submit 3-7 documents to us
No paperwork, no branch visits — 100% online